
Bought, not listed: Europe’s photonics startups exit reality
At PIC Summit Europe 2026, experts debated why most photonics companies are more likely to be acquired than to go public.
Published on November 10, 2026
© PIC Summit
Mauro swapped Sardinia for Eindhoven and has been an IO+ editor for 3 years. As a GREEN+ expert, he covers the energy transition with data-driven stories.
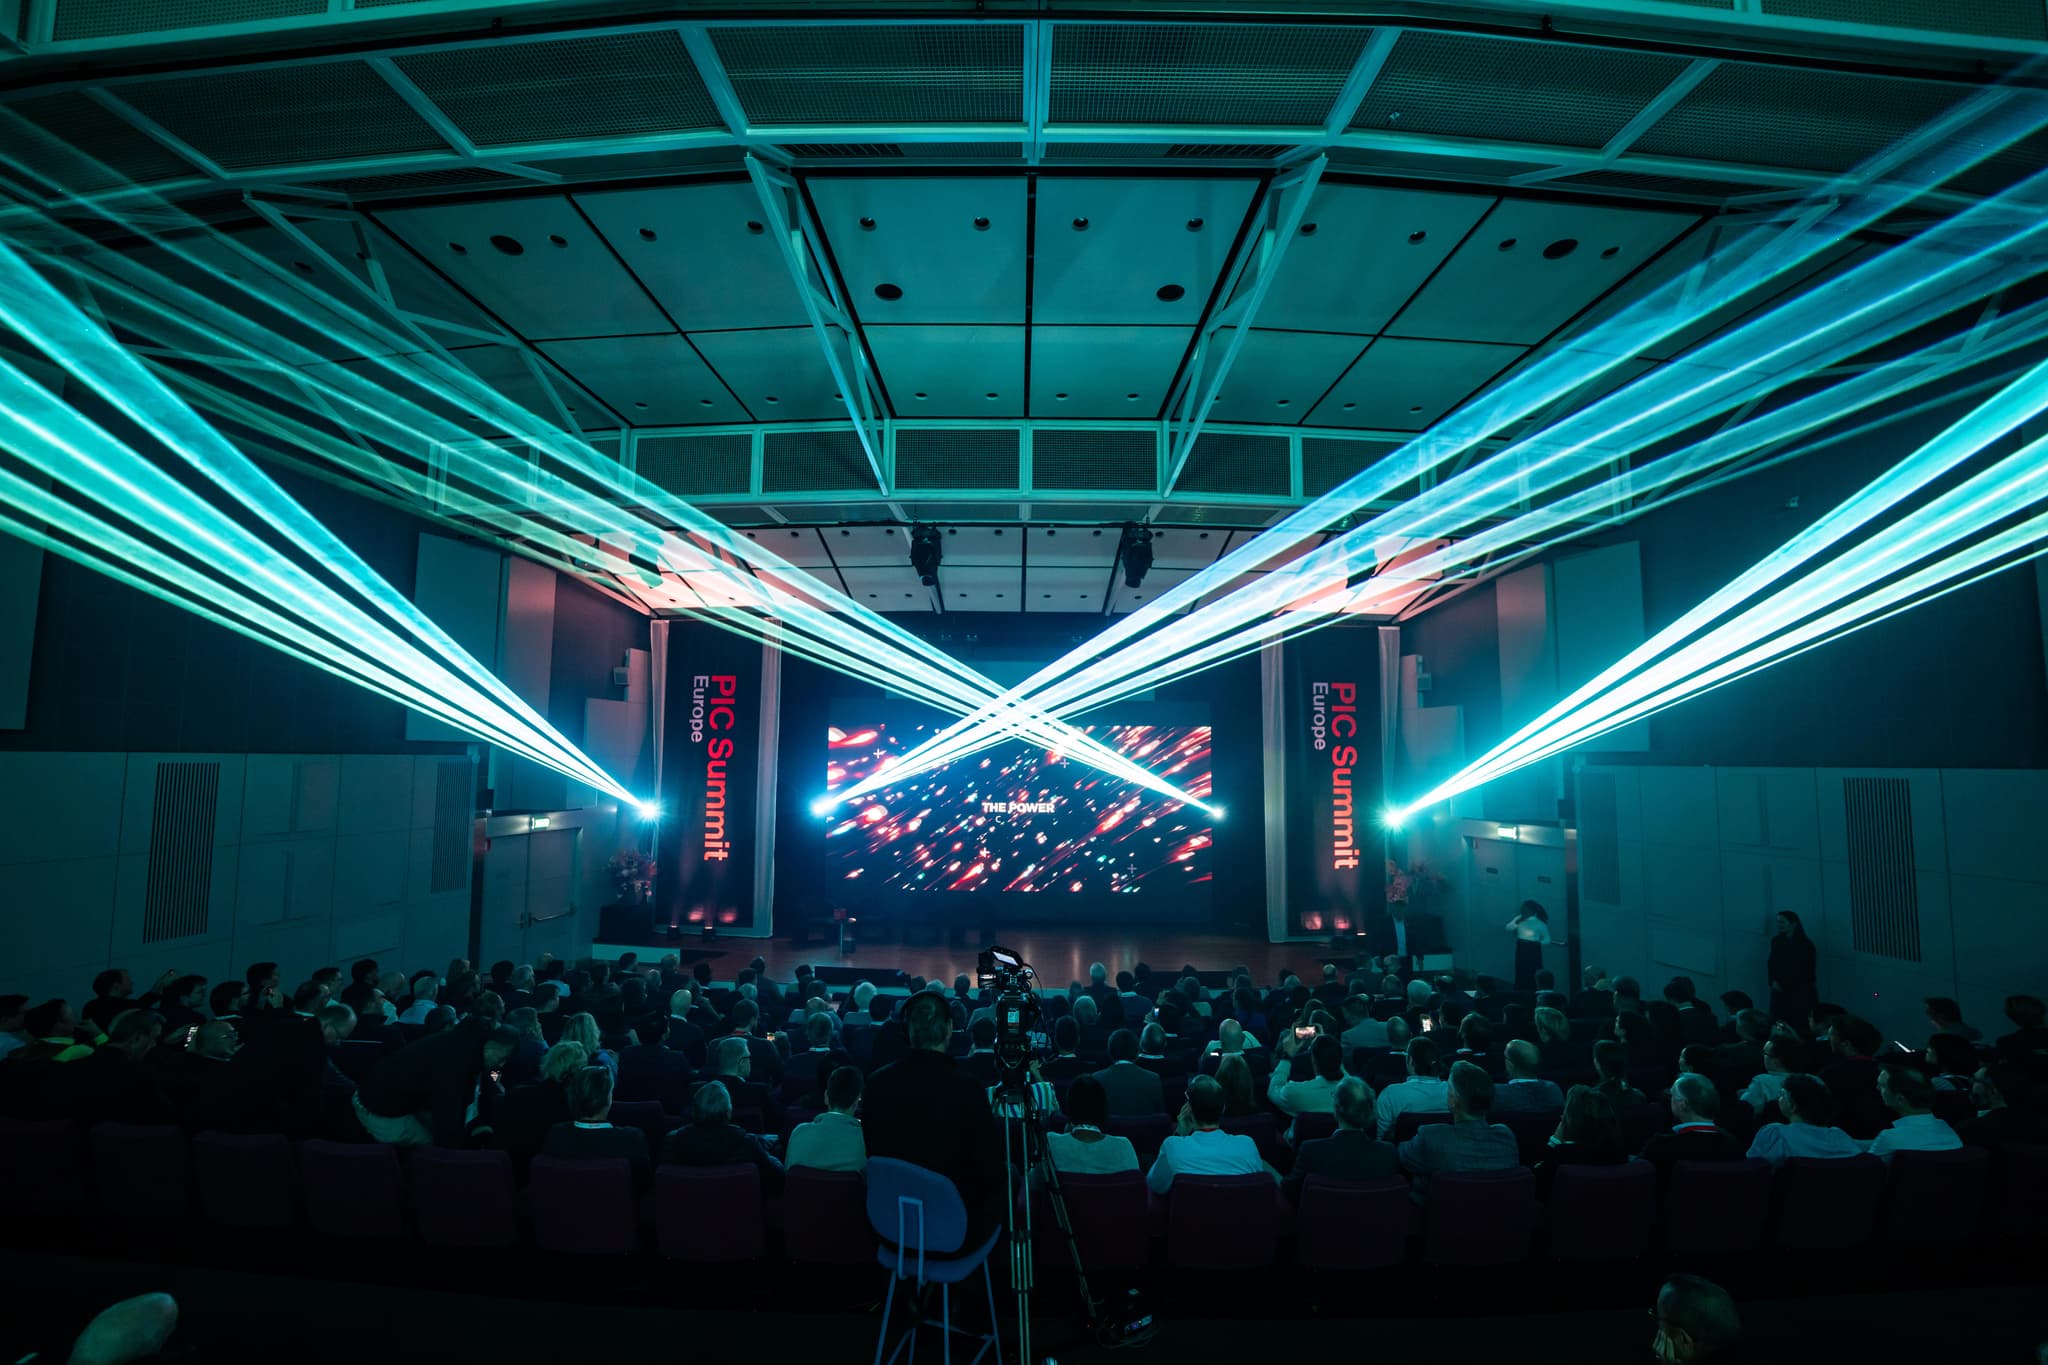
Every startup investor eventually needs an exit. Yet in venture capital, it is the conversation few people plan for. That was the starting point of "The Deep Tech Exit Strategy," a panel at last week's PIC Summit Europe in Eindhoven. The event on photonic chips was organized by the nonprofit Photon Delta, and focused on integrated photonics.
PhotonDelta CFO Laurens Weers moderated the panel. "I used to work for companies owned by private equity, and private equity really is about: we're buying a company, but what's our exit path? We work deliberately towards that," Weers said. "But then you go to venture capital, and suddenly we don't talk about, hey, what's your exit? We all say, well, I want an IPO. Is that realistic?"
An IPO, initial public offering, is the process where a private company offers its shares in stock markets. His reasoning was to start with the end in mind. Scaling deep tech costs a lot of money, and an investor who can see a path to an exit is more likely to provide it. Joining him on stage were Vincent Kamphorst, partner at venture capital firm Innovation Industries; Torsten Vahrenkamp, co-founder and CEO of photonics equipment maker ficonTEC; and Bedwyr Humphreys, investment director at Lam Capital, the venture arm of Lam Research.
Six years or twelve?
Weers opened with a provocation: would you rather have a €200 million exit after six years, or a €1 billion exit after 12? The panel first agreed on the quicker option, until Kamphorst realized he had misheard the figures and switched sides. Innovation Industries can invest up to roughly €75 million in a single company, with fund lifetimes of 12 years or more. "We're in it to build the larger companies, and sometimes it delays," he said. "We have the ability to stay the course."
Vahrenkamp, who now invests in young photonics companies with money from ficonTEC's own exit, held his ground. "In the ecosystem I'm investing in, a €200 million valuation looks feasible," he said. A billion euros in Europe is possible, he acknowledged, but "it's so far out, so far outside my capabilities, that I don't see a clear path."
Weers pointed to the wider benefit of faster exits. A vibrant exit climate creates serial founders, he argued, and the money flows back into the ecosystem, which matters in a region where scale-up capital is scarce.
Humphreys warned of a different trap. A company whose numbers look on course for a billion may receive an offer at around €200 million, and its board may push on without fully weighing the risks of scaling, capturing a market and competing. His advice to founders: "Be very clear with your board where everything is."
Why PIC companies get bought
For many photonic integrated circuit (PIC) startups, Kamphorst argued, the IPO question is largely academic. Equipment makers can grow into standalone companies, even if they eventually need to build a global service network. Fabless PIC designers selling into datacom face very different dynamics. Their customers are few, cash-rich and highly consolidated, and a startup that solves a critical bottleneck in their systems quickly becomes strategic.
"What you don't want, if you have a 100 billion addressable market, is to be reliant on something that may have a 1 billion addressable market that may determine your success," he said. "So there is a huge incentive and large strategic value to start to see if you can buy these type of companies."
The bar for going it alone is also high. A startup must prove not only its technology, but its product, its quality and its ability to deliver millions of units, while an IPO demands predictable revenue and a diversified customer base. "For a lot of the PIC companies, the reality is that the chance of a merger and acquisition (M&A) is just much larger than going all the way to an IPO," Kamphorst said.
Sell first, get bought later
Often, Kamphorst added, an acquisition happens almost by drift. A company making an external light source for co-packaged optics, for example, may win interest from a large customer, only to discover its supply chain cannot yet serve them. "They offer to help, but then you somehow get tied up, and in a very natural way that can go into an M&A direction."
Weers recognized the pattern. He once worked for an LED-driver company aiming for world dominance that was acquired by the largest lighting company in the US, precisely because it sold to them. "You have to be able to sell your product," he concluded, "and then strategics will come."
Vahrenkamp drew the same lesson from his seed portfolio, which has produced five exits so far, all of which stayed in Europe. The companies that failed did so mainly because of the team. "You have to be able to sell it," he said. "Either you bring somebody into the team who is able to sell it, or somebody in the team is a main seller. Without this component, you will not be successful."
Humphreys described the ideal outcome from a buyer's side: "You get your startup to the point where everyone's just going, well, I don't want to miss that, I don't want my competition getting that." Even then, corporate due diligence takes time. "It's not as if it's Friday and then by Monday you've made an offer."
Capital catching up
Vahrenkamp also sees a downside. From ficonTEC's vantage point as a toolmaker for young startups, ambitious teams are sometimes sold off before they can scale, a decision he believes is often driven by investors rather than founders.
Kamphorst was upbeat about the capital available for scaling. Five years ago, a €20 million round was large; now European deep tech companies raise €100 million to €300 million, and Innovation Industries is targeting a €1 billion fund. Europe does not excel at exits, he admitted, but its fundamentals are strong: "In the US companies are excelling in pitching with limited substance, and here it's the other way around."
For Humphreys, that substance is what ultimately creates the exit. "If you have something that is strategically important for the larger companies," he said, "then they'll come to you."